How to set a stop loss with ATR — The ATR Race
Lesson · Risk & sizing · September 30, 2026
Olympia publishes educational content for learning purposes only. Past performance is not indicative of future results. Nothing here is investment advice.
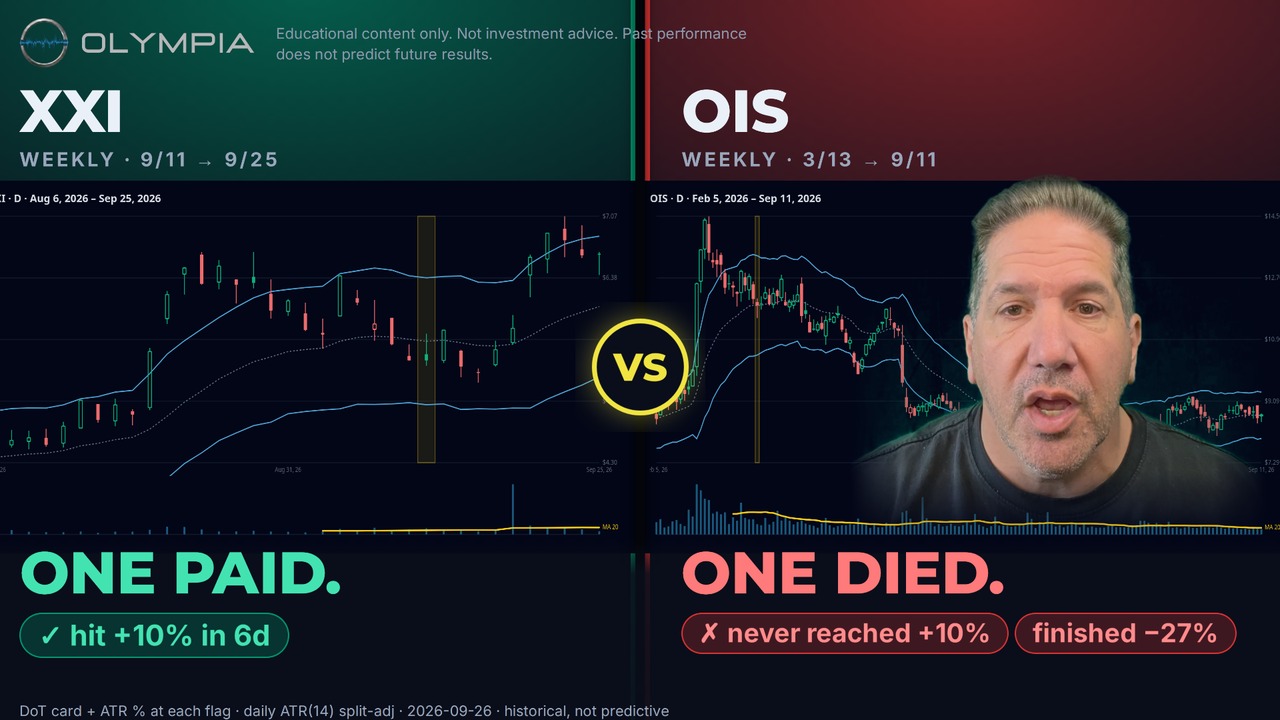
Two flags from the same scanner: one paid, one died. The ATR number didn't call either one. What it tells you is how rough the ride gets and how much room the trade needs. Then the stop: why it's measured in the stock's own ATR instead of a flat 10%, and why a wider stop doesn't have to mean a bigger loss.
The lesson in writing
Hi, I'm Mike, lead data researcher and developer of Olympia, and we're here to talk a little bit about how the product works and what it can do for you.
Here we have two charts that our models flagged. They don't always win — sometimes they do, sometimes they don't. One of them took its time and ground out the win. The other never reached it.
Now the breath of each. When they were flagged, one was moving about seven percent a day. The other was moving about the same. Nearly the same breath, opposite endings.
What it is
So here's the lesson about that number. It's the ATR — the average true range. It isn't telling you which one wins. It tells you something else.
What it tells you is how rough the ride is going to get. How the fight is going to look, and how bloodied each opponent will be at the end of that fight. And about how much room that trade needs to move and succeed.
A small breath, small swings, tighter room. A big breath, big swings — and a stop parked inside that breath, you are a target waiting to be shot out of the sky.
That dial never picks the winner. What it tells you, every single time, is the size of the swings on the way, and how much room your plan's gonna need.
How it's worked out
Every stock has a normal day. Average true range tells you how big that day is going to be.
Start with one day: the high minus the low — how far the price travelled. “True” means the gap counts too: if it opened well above or below the day before's close, that jump is part of the move for that day.
Now do that for the last fourteen days and average them. That's the ATR, and it comes out in dollars. Divide it by the price and you get a percent — seven percent means that name swings about seven percent on an ordinary day.
Then the stop is measured in those, not in a flat percentage. Ten percent is a different bet on every stock: on calm names, eighty-five of every hundred winners never dipped past about seventeen percent before the move paid; on the wildest third, about forty-three.
On the name in the video, about three of its own ranges down stopped out twenty-five of every hundred winners; four and a half, fifteen; five and a half, ten. The stop sits outside the stock's normal wiggle, so an ordinary day can't take you out.
And a wider stop doesn't mean a bigger loss. The stop's distance belongs to the stock; the loss belongs to you — one or two percent of your account. A wider stop simply buys fewer shares, and the amount at risk never moves.
Where Olympia calculates it
You don't have to work any of that out. Olympia calculates it for every signal.
It sets the entry zone — one ATR either side of today's centre, measured on the same clock the signal runs on. On the scanner it has a column of its own, ATR % (daily): the average true range over fourteen daily bars as a percent of the close.
And where you log a trade it lays out the stop menu with the counts in the box beneath it, works the share count off your own risk, and keeps the floor once a trade has paid.
Safe going in, safe on the account, the win kept — all decided before you're in, when you're thinking clear.
The dip figures: Olympia's stop-width study, 24 August 2026 — served-board winners, split in thirds by ATR, measured at the depth that eighty-five of every hundred never went past before the move armed. The stopped-out counts are the measured ladder's three rungs, converted into one example name's own range. The pair: Olympia's Death of a Trade card, 26 September 2026 — every signal tracked to its finish, wins and losses both. Historical, not predictive.